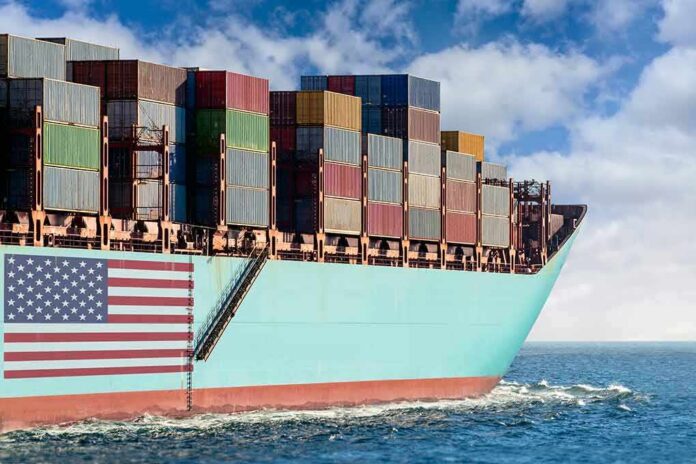
The most consequential fact about China’s navy is not any single warship — it’s the factory floor beneath it. China now builds ships using the same yards, the same steel supply chains, and often the same workforce for container vessels and destroyers alike, which means its commercial shipbuilding dominance functions as a standing subsidy for naval expansion that no rival democracy can easily replicate.
Key Points
- China’s shipyards produced 53.69 million deadweight tonnes in 2025, 56.1% of global output, and captured 69% of new orders worldwide.
- The PLA Navy commissioned more than 18 new warships in 2025, including the aircraft carrier Fujian (Type 003), delivered at Sanya Naval Base on November 5, 2025.
- The United States produces roughly 0.1% of global commercial shipbuilding tonnage — a handful of vessels a year against China’s output of over 1,000.
- Washington’s response leans heavily on South Korean and Japanese shipbuilders, including Hanwha’s 2024 purchase of the Philadelphia Shipyard.
- A pause in new Chinese destroyer starts in late 2025 appears tied to a generational design leap, not a slowdown in capacity.
The Industrial Base That Makes the Numbers Possible
China’s Ministry of Industry and Information Technology reported that the country’s shipyards completed 53.69 million deadweight tonnes in 2025, an 11.4% increase over the prior year, while securing 107.82 million DWT in new orders and holding a backlog of 274.42 million DWT — 66.8% of the entire global orderbook. Those are commercial figures, covering tankers, container ships, and bulk carriers. But the significance for naval planners is structural: the same shipyards, the same welders, the same steel mills and crane infrastructure that produce civilian tonnage also build warships. China State Shipbuilding Corporation, the state-owned conglomerate that dominates this output, operates roughly a dozen yards responsible for virtually all of the PLA Navy’s modern fleet.
By the first half of 2026, that lead had widened further. Chinese yards completed 36.5 million DWT, up 51.2% year over year, while new orders surged 173.1% to 121.06 million DWT — an 82.3% share of everything ordered on earth during that stretch. No other shipbuilding nation, including South Korea at roughly 27% of global output, operates at a scale that permits this kind of dual-use flexibility. The United States, by contrast, builds an estimated three to eight commercial ships a year, a collapse from the 70-plus vessels and 180,000 shipyard workers it fielded in 1975.
What the PLA Navy Actually Commissioned
Set against that industrial base, 2025’s naval delivery schedule reads as the predictable output of a system built for volume. The PLA Navy commissioned more than 18 new warships during the year, a figure defense-sector reporting treats as a floor rather than a ceiling, since Chinese submarine construction in particular is deliberately obscured. The marquee addition was the aircraft carrier Fujian, China’s third carrier and its first equipped with electromagnetic catapults, commissioned November 5, 2025 at Sanya Naval Base in a ceremony attended by Xi Jinping. Surface combatant deliveries included seven Type 052D destroyers, one Type 055 large destroyer, a Type 075 amphibious assault ship, and six frigates split between the Type 054A and the newer, all-electric Type 054B, whose lead ship entered service in January 2025.
Early 2026 tracking has since identified additional hulls commissioned but not yet formally announced, including a second Type 055 destroyer and further Type 903A replenishment oilers — support vessels that extend a fleet’s operating range and are easy to overlook but essential to any navy intending to operate far from home waters. China currently fields 68 submarines, 12 of them nuclear-powered, a number roughly matching the U.S. submarine fleet even as American commentary continues to treat the PLA Navy as a coastal force. It is not.
Why a Pause in Destroyer Starts Is Not a Slowdown
Chinese shipyards reportedly paused new Type 052D and Type 055 destroyer starts at major yards in late 2025 — a fact that on its face might read as reduced momentum. The more persuasive reading, consistent with satellite and production evidence, is that the pause reflects a transition rather than a retreat: China appears to be moving from incremental upgrades of a design lineage it spent two decades perfecting toward a genuinely new architecture built around integrated electric propulsion, a technology that allows a warship to route power flexibly between propulsion, radar, and future high-energy weapons. A next-generation destroyer class near 9,000 tons, an improved Type 055 successor near 12,000 tons, and mass production of the Type 054B frigate all point toward a fleet designed as a networked system of sensor and weapons nodes rather than a collection of independent ships.
Where the United States Stands, and How It Is Responding
Washington has not disputed the scale gap; if anything, its own institutions have quantified it in stark terms. The U.S. Government Accountability Office found Navy shipbuilding programs running billions over budget in 2026, with Arleigh Burke-class destroyers delayed 22 to 58 months and the Columbia-class submarine at least 18 months behind schedule. The policy response has centered on allied capacity rather than domestic revival alone. South Korea’s Hanwha purchased the Philadelphia Shipyard in 2024 for $100 million and has pledged $150 billion toward reviving U.S. shipbuilding as part of a broader $350 billion bilateral package; the yard currently produces roughly one to one-and-a-half ships annually against Hanwha’s Korean output of about one per week. The Navy has separately explored purchasing warships outright from Japan, South Korea, and Turkey to expand fleet numbers on a timeline domestic yards cannot match.
These are not signs of parity on the horizon. They are signs that American planners have accepted the scale of the problem and are pursuing the fastest available offset — allied industrial capacity — while domestic shipbuilding, hollowed out since the 1980s by the end of Cold War-era subsidies and competition from Japan and Korea, rebuilds workforce and infrastructure over what analysts uniformly describe as a multi-decade horizon.
What the Trajectory Means
Nothing in the current data suggests China’s shipbuilding lead is transient. Forecasts built on five-year trend lines expect China to hold 55–70% of global completions, orders, and backlog for the foreseeable future, with naval commissioning tonnage remaining the world’s highest. The strategic consequence is not that China will out-produce the U.S. Navy ship-for-ship in some symmetric race — it already does, and by a wide margin — but that the industrial depth behind that production gives Beijing options in a sustained conflict that a smaller, contract-dependent shipbuilding base cannot match. That asymmetry, more than any single carrier or destroyer count, is the durable fact policymakers on both sides of the Pacific are now building strategy around.
Sources:
19fortyfive.com, english.www.gov.cn, dredgewire.com, en.wikipedia.org, vpk.name, macaonews.org, xindemarinenews.com, news.cgtn.com, apps.dtic.mil